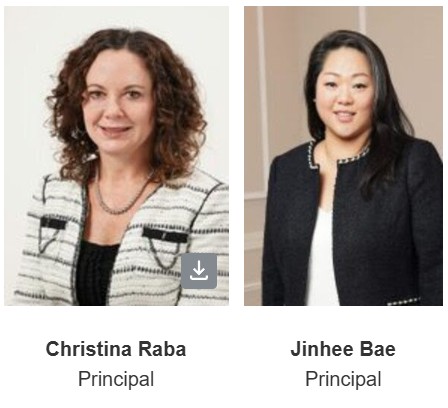
Power Law Firm Joins Winne Banta

trusts attny

We’re pleased to announce that Christine Raba and Jinhee Bae, principals of Power Law Firm LLP, are joining the firm.

A Hackensack-based practice concentrating in trusts, estates, and elder law, led by members Christine Raba and Jinhee Bae, brings dedicated depth that expands Winne Banta’s elder law and special needs planning services while complementing the trusts and estates practice the firm’s clients have long relied on.

Raba’s and Bae’s practice focuses on tax-efficient family wealth transfers, asset protection, and special needs planning. 

Raba and Bae join Winne Banta as principals, bringing their team and focused experience to the firm’s established tax and trust and estate practices, giving current and future clients access to a broader, full-service platform for planning that spans generations, all under one roof.

“I have long admired the work Christine, Jinhee, and their team have done at Power Law Firm, and we are thrilled to welcome them to Winne Banta,” said Joseph L. Basralian, president of Winne Banta. “Their elder law and special needs experience allows us to offer even more to the individuals and families we serve. It means our clients, and the clients who will come to us in the years ahead, have trusted guidance for some of life’s most important and sensitive planning decisions.”

With the addition, Winne Banta clients now have a single destination for estate planning, trust and estate administration, elder law, special needs planning, and asset protection, complementing the firm’s established strengths in litigation, finance and corporate services, real estate, land use and zoning, and tax.

trusts button

Estate planning guidance for your family

Learn about Winne Banta’s tax, trusts and estates services, or contact the firm to discuss your circumstances.
2025 Estate, Gift and GST Tax Proposals: May Legislative Update

Historical context. Archived May 2025 legislative update. The discussion below concerns proposals released before final legislation. It does not describe current law. For current federal guidance, see the IRS estate and gift tax resources linked below.

On May 9, Republicans on the House Ways and Means Committee released the first wave of their tax proposals as part of the overall budget reconciliation process. The Committee has scheduled a markup of tax reconciliation measures for May 13. As this is just the opening salvo, we expect new proposals, changes, and constant updates until the President signs a final bill.

  • The unified estate and gift tax exemption is made permanent to an inflation-indexed $15 million for taxable years beginning after Dec. 31, 2025. The generation-skipping transfer tax exemption is also permanently increased to an inflation-indexed $15 million.

Other important proposals that you will find of interest are:

  • Proposals making the rates for individuals, estates, and trusts enacted in the Tax Cuts and Jobs Act (TCJA) permanent with modifications for inflation. The expiration date of the standard deduction from TCJA is removed, and temporary increases in the standard deduction result in a deduction of $16,000 for individuals, $24,000 for heads of households, and $32,000 for joint returns. These increases would expire Jan. 1, 2029.

  • For Homeowners, the $750,000 ($375,000 married individual filing separately) limitation on principal residence acquisition indebtedness is made permanent, as is the exclusion of interest on home equity indebtedness from the definition of qualified residence interest.

  • Five modifications to qualified business deductions for pass-through entities under section 199A. These include making the deduction permanent and increasing the calculation amount from 20% to 22%. There is also the opportunity in some instances to apply the benefit to income derived from a specified service trade or business, which has historically been unavailable. An inflation index is also added after 2025.

Winne Banta Basralian and Kahn recommends that you schedule a meeting with one of the attorneys in our Tax, Trusts and Estates Department, which will allow you and your family to consider and finalize the most comprehensive and effective estate plan that fits your specific needs and goals. Do not overlook and forgo the value of the extra gifting power available to you while the exemption remains at a historical high.

Co-Chairs of the Tax, Trusts & Estates Department:

Martin J. Dever, Jr. mdever@winnebanta.com
Jonathan Kukin jkukin@winnebanta.com

Partners of the Tax, Trusts & Estate Department:

Arthur I. Goldberg agoldberg@winnebanta.com
Peter J. Bakarich, Jr. pbakarich@winnebanta.com
Doris Brandstatter dbrandstatter@winnebanta.com


Associates of the Tax, Trusts & Estate Department:

Marley A. Guerrera mguerrera@winnebanta.com
Sara E. N. Lerner slerner@winnebanta.com

Estate planning guidance for your family

Learn about Winne Banta’s tax, trusts and estates services, or contact the firm to discuss your circumstances.

For official information, review IRS estate and gift tax guidance.

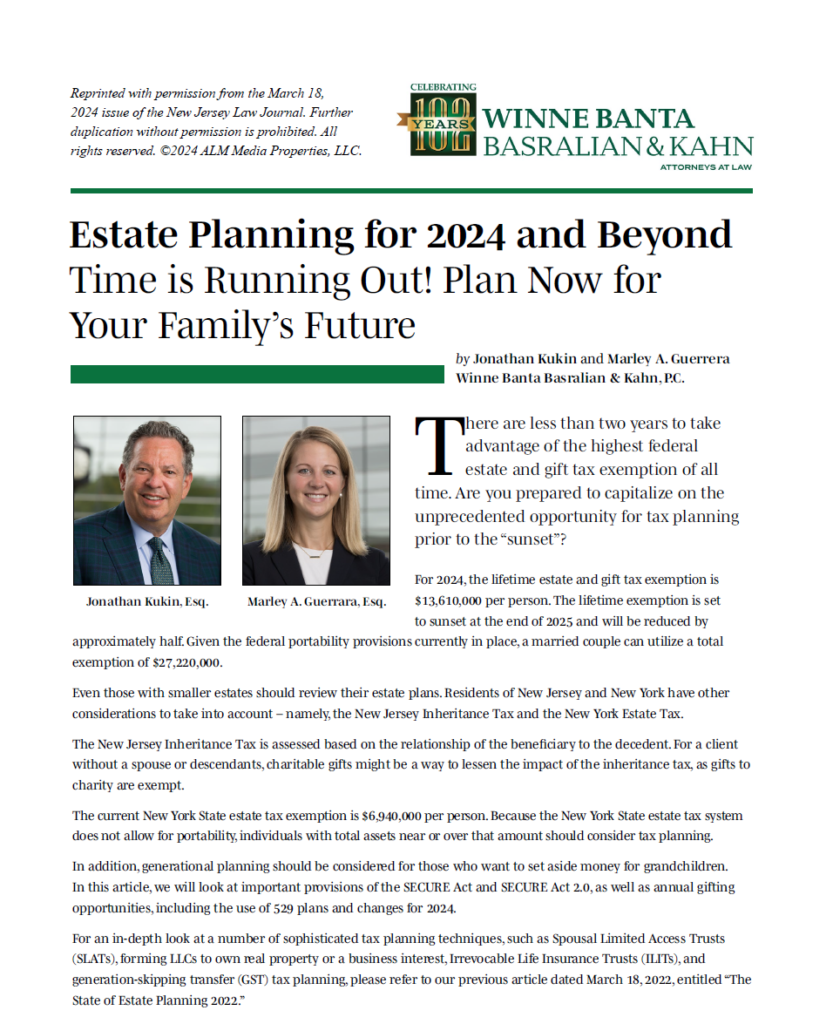
Estate Planning for 2024 and Beyond: Archived Article

Historical context. Historical article announcement from March 2024. The quoted discussion of a future exemption sunset reflects the law at that time and should not be relied on as current tax guidance.

An article by Winne Banta Basralian & Kahn’s Jonathan Kukin and Marley Guerrara, “Estate Planning for 2024 and Beyond: Time Is Running Out! Plan Now for Your Family’s Future” was published recently in The New Jersey Law Journal.  In the article, Jonathan and Marley noted, “There are less than two years to take advantage of the highest federal estate and gift tax exemption of all time.  Are you prepared to capitalize on the unprecedented opportunity for tax planning prior to the ‘sunset’?” 

estate planning for 2024 and beyond

Estate planning guidance for your family

Learn about Winne Banta’s tax, trusts and estates services, or contact the firm to discuss your circumstances.

For official information, review IRS estate and gift tax guidance.

2021 Year-End Estate and Gift Tax Planning Outlook

Historical context. Archived 2021 year-end planning outlook. References to a future 2025 exemption sunset describe the law and expectations at that time and should not be used as current tax guidance.

As 2021 has come to an end and you begin your estate planning preparations for 2022 and beyond, it is important to reflect upon what almost happened this past year.

Under current law, the lifetime estate and gift tax exemption is set to sunset at the end of 2025, at which time the exemption amount will be reduced by half.  Although the most hastily discussed gift and estate tax rules of this year (i.e., an early sunset of the lifetime exemption amount) were not placed into effect, the proposed new law would have halved the allowable lifetime estate and gift tax exemption by the end of 2021.  While it appears, any immediate changes are on hold, this does not mean one should be complacent with their current estate plan. The changes to the gift and estate tax rules on the horizon should motivate you to review your current plan.

Winne Banta Basralian and Kahn recommends that you schedule a meeting with one of the attorneys in our Tax, Trusts and Estates Department, which will allow you and your family to consider and finalize the most comprehensive and effective estate plan that fits your specific needs and goals. Clearly, you should not remain quietly on the sidelines and defer your important planning until the current exemption sunsets at the end of 2025.  Do not overlook and forgo the value of the extra gifting power available to you while the exemption remains at a historical high.

As of January 1, 2022:

  • Annual Exclusion Increases to $16,000 from $15,000
  • Lifetime Estate and Gift Tax Exemption Increases to $12,060,000 from $11,700,00
  • Generation Skipping Tax Exemption Increases to $12,060,000 from $11,700,00
  • Grantor Trusts will remain an effective way to shift wealth to the next generation

Co-Chairs of the Tax, Trusts & Estates Department

Martin J. Dever, Jr.    mdever@winnebanta.com

Jonathan Kukin         jkukin@winnebanta.com

Partners of the Tax, Trusts & Estate Department:

Arthur I. Goldberg        agoldberg@winnebanta.com

Peter J. Bakarich, Jr.    pbakarich@winnebanta.com

Associates of the Tax, Trusts & Estate Department:

Doris Brandstatter               dbrandstatter@winnebanta.com

Victor Manuel Nazario III    vnazario@winnebanta.com

Marley A. Guerrera              mguerrera@winnebanta.com

Estate planning guidance for your family

Learn about Winne Banta’s tax, trusts and estates services, or contact the firm to discuss your circumstances.

For official information, review IRS estate and gift tax guidance.

Scroll to Top